

Aisg Connector Market Size, Share, Growth, and Industry Analysis, By Type (Plug AISG Connector, Socket AISG Connector), By Application (Control Cables, RET, TMA, Smart Bias-T, Signal Splitter, Lightning Protection Devices, Others), Regional Insights and Forecast to 2035
 Buy Now


Aisg Connector Market Overview
The global Aisg Connector Market is anticipated to grow from USD 1042.63 Million in 2026 to USD 1232.04 Million by 2035, registering a CAGR of 1.87% during the forecast period 2026-2035.
The Aisg Connector Market is supported by continuing investment in wireless telecommunications infrastructure, remote electrical tilt antenna systems, and reliable outdoor connectivity. Plug AISG Connector products account for approximately 55% of global demand, reflecting their widespread use in antenna control cables and telecom equipment assemblies. AISG connectors provide electrical interfaces for transmitting control information and direct-current power between compatible network components. Manufacturers increasingly emphasize weather-resistant housings, corrosion-resistant contacts, secure locking mechanisms, and dependable electrical performance. The adoption of multiband antennas and remotely managed radio infrastructure creates recurring demand for compatible interconnection products. Network operators also require replacement connectors and control cable assemblies during infrastructure maintenance, antenna upgrades, and site modernization. These requirements sustain demand for standardized connectivity products across established and emerging telecommunications markets.
The USA represents an important national market because of its extensive wireless infrastructure, established telecommunications operators, and continuing network modernization activities. North America accounts for approximately 22% of global AISG connector demand in the reported regional market assessment, with the United States representing the largest national contributor. Telecom infrastructure providers use AISG connectors in remote electrical tilt systems, antenna control assemblies, and compatible tower-mounted equipment. Commercial purchasing decisions emphasize electrical reliability, environmental sealing, and compatibility with existing installed infrastructure. Manufacturers and distributors supply standardized connector configurations and cable assemblies to support maintenance operations and equipment upgrades. The demand outlook is influenced by antenna replacement programs, network densification, and the continued operation of established wireless sites.
Get Comprehensive Insights into the Market’s Size and Growth Trends
 Download FREE Sample
Key Findings
- Key Market Driver: Expansion and modernization of wireless antenna infrastructure remain the primary growth drivers, with approximately 58% of reported AISG connector demand associated with telecommunications network development and related equipment upgrades.
- Major Market Restraint: Specialized materials, environmental protection requirements, and manufacturing complexity increase product costs, with approximately 30% of reported market challenges attributed to advanced connector production and procurement expenses.
- Emerging Trends: Weather-resistant construction and improved electrical reliability are shaping product innovation, with approximately 44% of reported connector development initiatives emphasizing environmental durability and reduced connection-related performance losses.
- Regional Leadership: Asia-Pacific leads the Aisg Connector Market with approximately 40% share of reported global unit demand, supported by extensive wireless infrastructure, manufacturing capabilities, and continuing antenna modernization.
- Competitive Landscape: SYSKIM maintains a notable market position with an estimated 18% share of global AISG connector shipments, supported by specialized product availability and demand for durable antenna-control interconnections.
- Market Segmentation: Plug AISG Connector leads 55% the product category, while RET remains the largest individual application with approximately 35% share, reflecting continuing demand for remotely adjustable antenna systems.
- Recent Development: Amphenol's AISG interconnection portfolio has supplied more than 20 million connector and cable assemblies internationally, with 55% demonstrating the established scale of standardized products supporting wireless infrastructure.
Latest Trends
The Aisg Connector Market is experiencing increased attention to environmental sealing, connector durability, and consistent performance in outdoor wireless infrastructure. Standard AISG control connections frequently use 8-pin circular connector arrangements designed to carry power and communication signals between compatible components. Manufacturers are improving contact materials, molded cable transitions, strain relief, and locking interfaces to support approximately 44% repeated maintenance and prolonged outdoor exposure. Products with IP67 protection when correctly mated are widely specified for installations exposed to moisture and airborne contamination. Network operators increasingly favor standardized components that simplify antenna replacement and reduce compatibility problems across equipment suppliers. The trend toward compact multiband antenna installations also encourages careful management of cable routing and connector accessibility. These requirements support demand for robust connector assemblies and accurately manufactured interfaces.
Another important trend involves the integration of standardized AISG connectivity into more complex antenna and remote control architectures. Commercial cable assemblies commonly support AISG 2.0 communication and provide compatible male and female interfaces for equipment connectivity. Manufacturers offer multiple cable lengths and connector arrangements to accommodate different equipment layouts. Improved electrical shielding and reliable contact retention help protect control communications within demanding radio installations. Telecom contractors increasingly request preassembled, tested cable products because field installation involves limited workspace and strict maintenance schedules. Product development therefore emphasizes practical installation, accurate labeling, mechanical stability, and dependable environmental protection. As operators continue modernizing existing sites, compatibility with installed antenna-control equipment remains an important consideration alongside newer connector designs.
Market Dynamics
Driver
"Wireless infrastructure modernization strengthens demand for reliable antenna connectivity."
Continuing development of mobile telecommunications infrastructure is the principal demand driver for AISG connectors. Approximately 58% of reported market demand is associated with wireless network expansion and modernization, particularly where antenna systems require remote electrical adjustment. Operators deploy standardized interconnections to support antenna-control communication and compatible power distribution. Remote adjustment capabilities can reduce the need for repeated physical intervention at elevated antenna installations. This is especially useful for operators maintaining numerous geographically dispersed sites. Connector suppliers benefit from new deployments, replacement cable requirements, and upgrades to existing antenna configurations. Demand remains connected to practical network engineering requirements rather than consumer electronics purchasing cycles.
Restraint
"Specialized manufacturing requirements increase equipment procurement costs."
The cost of high-reliability connector production remains an important restraint, particularly for buyers managing extensive telecommunications infrastructure. Approximately 30% of reported market challenges are linked to specialized materials, production requirements, and related procurement expenses. Outdoor connectors require appropriately protected contact surfaces, precise mechanical tolerances, durable insulation, and effective sealing. These requirements increase manufacturing complexity compared with simpler indoor electrical connectors. Network contractors must also consider cable assembly quality, installation compatibility, and long-term replacement availability. Price-sensitive buyers may postpone nonessential replacement activities when existing equipment remains functional.
Opportunity
"Antenna upgrades and replacement assemblies create specialized supply opportunities."
Infrastructure modernization across Asia-Pacific creates opportunities for suppliers of standardized antenna-control interconnections. The region represents approximately 40% of reported global AISG connector unit demand, supported by substantial wireless equipment deployment and established component manufacturing capabilities. China, India, Japan, and Southeast Asian countries maintain demand for antenna control assemblies, replacement cables, and compatible network accessories. Manufacturers can expand through relationships with telecom equipment suppliers, installers, and specialist distributors. Product localization, dependable inventory, and consistent electrical specifications are important competitive factors. Suppliers offering complete cable assemblies alongside individual connectors can address maintenance requirements more effectively than businesses supplying isolated components.
Challenge
"Interoperability and harsh outdoor conditions complicate long-term connector reliability."
Maintaining compatibility across telecommunications equipment is a continuing challenge because operators may deploy antennas and controllers supplied by several manufacturers. The AISG 2.0 communication protocol supports standardized control functions, but correct physical wiring, electrical characteristics, and equipment compatibility remain necessary. Incorrect connector selection can interrupt antenna-control communication or create maintenance difficulties. Installers must verify connector gender, cable length, mating characteristics, and supported equipment interfaces before completing connections. The presence of multiple installed equipment generations increases the importance of clear product documentation. Manufacturers must maintain reliable production tolerances while supporting replacement requirements for established infrastructure.
Aisg Connector Market Segmentation
Get Comprehensive Insights on the Market Segmentation in this Report
Download FREE Sample
Get Comprehensive Insights on the Market Segmentation in this Report
Download FREE Sample By Types
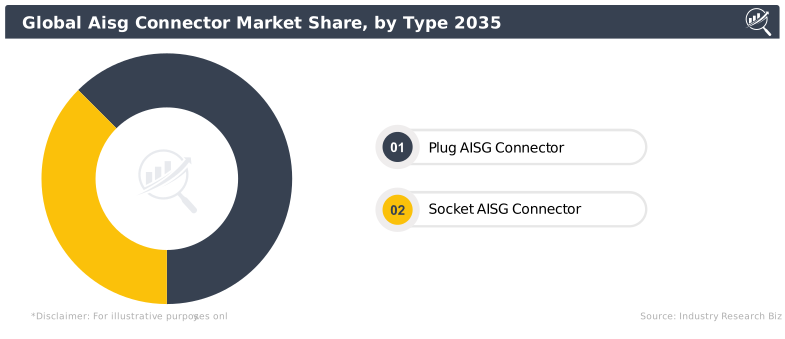
Plug AISG Connector: Plug AISG Connector products account for approximately 55% of the reported market, making them the leading connector type. Plug configurations are used in compatible antenna-control systems and cable assemblies where removable electrical connections are required. Manufacturers emphasize reliable pin alignment, mechanical retention, and protective sealing. Product demand is supported by installation, replacement, and equipment modernization activities. Telecom purchasers prioritize dependable compatibility and predictable connector quality when selecting plug assemblies for outdoor infrastructure. Plug connectors commonly use 8-pin circular interfaces conforming to applicable AISG equipment specifications. Their performance depends on accurate mating with compatible socket assemblies and appropriate environmental sealing. Manufacturers develop preassembled products to reduce field wiring requirements and installation variation.
Socket AISG Connector: Socket AISG Connector products represent approximately 45% of the reported market, providing complementary interfaces for compatible antenna-control equipment. Socket arrangements support electrical connections between equipment and removable cable assemblies. Manufacturers focus on reliable contact retention, environmental protection, and accurate alignment. Demand is influenced by antenna equipment production, maintenance requirements, and replacement of damaged interfaces. Suitable socket construction helps maintain dependable communication and power delivery within compatible control systems. Socket assemblies are frequently designed to operate with 8-pin mating connectors and established AISG cable arrangements. Their effectiveness depends on correct mounting, secure sealing, and electrical compatibility. Equipment manufacturers may integrate socket interfaces into antenna-control products to simplify external connections.
By Applications
Control Cables: Control Cables account for approximately 27% of reported AISG connector application demand. These assemblies connect compatible antenna-control devices and carry required electrical signals and power. Telecom contractors use preassembled products to reduce installation complexity and maintain consistent wiring. Manufacturers offer different lengths and connector configurations for varied tower arrangements. Demand is supported by new equipment deployment, network maintenance, and replacement of weather-exposed assemblies. Standard control assemblies may include 6 internal conductors supporting communication and power connections, depending on the product design. Cable selection considers conductor dimensions, shielding, jacket materials, and installation conditions. Manufacturers emphasize durable strain relief and reliable molded connections.
RET: RET represents approximately 35% of reported application demand, making it the leading application category. Remote electrical tilt equipment enables compatible antenna systems to adjust electrical coverage characteristics without routine physical repositioning. AISG connectors provide standardized control interfaces supporting these functions. Operators prioritize dependable connectivity because control interruptions can complicate antenna management. Demand is associated with multiband equipment deployment, existing site modernization, and replacement of damaged control assemblies. RET cable products commonly support AISG 2.0 communication and use standardized circular connector arrangements. Installers must confirm compatibility between controllers, antenna components, and cable assemblies. Proper sealing and cable management are important because connections may remain exposed for extended periods.
TMA: TMA applications represent approximately 15% of reported demand within the market's principal application classification. Tower Mounted Amplifier equipment can require compatible control and power interfaces depending on system architecture. Connector reliability is important because tower-mounted components operate in exposed locations. Manufacturers emphasize weather resistance, secure mating, and electrical consistency. Demand depends on network equipment configurations, maintenance requirements, and replacement schedules. TMA installations may incorporate 8-pin control interfaces where equipment specifications require AISG-compatible connectivity. Suppliers must provide appropriate cable and connector configurations for the selected amplifier system. Reliable sealing helps reduce exposure-related failures. Telecom technicians value clearly identified components and accessible replacement inventory.
Smart Bias-T: Smart Bias-T accounts for approximately 12% of reported application demand. Compatible devices can combine antenna-system power delivery and control connectivity in specialized configurations. AISG interfaces support relevant control connections where specified by the equipment manufacturer. Product requirements emphasize dependable electrical characteristics, weather protection, and installation compatibility. Demand is influenced by existing network architectures and equipment modernization activities. Selected Smart Bias-T products employ AISG 2.0 control arrangements alongside dedicated radio-frequency interfaces. Manufacturers must maintain appropriate electrical separation and compatible connections within the system. Installation requirements vary according to device design and antenna architecture. Proper technical documentation helps prevent incorrect connections.
Signal Splitter: Signal Splitter applications represent approximately 6% of reported AISG connector-related demand. Compatible splitting or distribution equipment may require standardized electrical interfaces for control functions in selected antenna installations. Manufacturers focus on reliable connector construction and mechanical compatibility. Demand depends on the architecture of installed telecommunications systems and the availability of suitable replacement assemblies. Telecom equipment may distribute signals across 2 or more paths, although individual splitter functionality varies considerably by design. AISG connectors are used for relevant control connections and should not be confused with the radio-frequency interfaces that carry communication signals. Correct component selection is therefore important. Suppliers emphasize clear labeling, dependable construction, and accurate technical specifications for specialized installations.
Lightning Protection Devices: Lightning Protection Devices represent an indicative 3% share in the normalized application allocation. These devices protect telecommunications infrastructure against specified electrical surge conditions, with compatible AISG connections used where system design requires control-interface protection. Product selection depends on electrical ratings, grounding requirements, and the configuration of connected equipment. Manufacturers prioritize dependable construction and appropriate protection specifications. Protected installations may require coordination between 2 essential measures: suitable surge-protection equipment and correctly designed grounding. Connector quality contributes to reliable continuity but cannot replace appropriate lightning-protection engineering. Equipment must be selected according to site requirements and applicable safety standards. Installation contractors also consider maintenance access, environmental sealing, and compatibility with existing antenna-control assemblies.
Others: Others represent an indicative 2% residual share within the normalized application allocation. This category covers additional specialized uses of compatible AISG interconnections that are not included in the principal application groups. Demand remains dependent on equipment architecture, installation requirements, and replacement activity. Manufacturers address these applications through customized assemblies and suitable standardized components. Specialized connections may require 2 different connector orientations or customized cable lengths to suit equipment layouts. Suppliers can provide technical assistance with pin configuration, mechanical fit, and sealing requirements. Low-volume applications frequently benefit from flexible manufacturing and accurate documentation. Product compatibility and reliable component availability remain important for maintaining installed telecommunications equipment.
Regional Outlook
Get Comprehensive Insights into the Market’s Size and Growth Trends Download FREE Sample
North America
North America represents approximately 22% of reported global AISG connector demand, supported by established telecommunications infrastructure and continuing antenna modernization. The United States and Canada require compatible connectors for remote electrical tilt equipment, control cables, and selected tower-mounted devices. Network operators prioritize dependable connections and standardized replacement products because many installations remain operational for extended periods. Regional suppliers emphasize product documentation, environmental sealing, and established distributor relationships. North American telecom contractors commonly use 8-pin AISG cable assemblies that support standardized electrical connections. Demand reflects ongoing infrastructure maintenance, antenna replacement, and equipment compatibility requirements. Manufacturers offering multiple cable lengths and reliable inventory can support installation schedules. Electrical testing and weather-resistant construction remain important procurement considerations. Established wireless infrastructure creates a continuing replacement market alongside new deployment activity.
Europe
Europe accounts for approximately 18% of reported global market demand. Germany, the United Kingdom, France, and other European countries support purchases through wireless network upgrades and telecommunications equipment manufacturing. Buyers emphasize interoperability, environmental performance, and appropriate regulatory compliance. Rosenberger and other specialist suppliers maintain product portfolios designed for demanding infrastructure applications. Network operators increasingly require well-documented control assemblies compatible with established antenna systems. European products commonly reference IEC 60130-9 for suitable circular connector arrangements. Manufacturers also address material restrictions, cable-jacket requirements, and mechanical durability. Infrastructure modernization creates demand for connector replacements and new control cable assemblies. Procurement teams consider installation reliability and long-term product availability. Accurate technical documentation remains important when supporting equipment from several suppliers across established networks.
Asia-Pacific
Asia-Pacific leads with approximately 40% of reported global unit demand. China, India, Japan, South Korea, and Southeast Asian countries support the market through wireless infrastructure activity and telecommunications component manufacturing. Regional manufacturers supply standardized connectors and complete cable assemblies for domestic and international customers. Demand is influenced by antenna replacement, network development, and cost-effective equipment procurement. Manufacturing capabilities strengthen the availability of specialized components. Regional suppliers commonly manufacture 8-pin AISG connector assemblies with weather-resistant housings and suitable control-cable construction. Telecom contractors require dependable products capable of handling varied installation conditions. Price competitiveness and production flexibility remain important advantages for regional manufacturers. Network operators also prioritize equipment compatibility during modernization. Established manufacturing clusters support international distribution and specialized product development.
Middle East and Africa
The Middle East and Africa contributes approximately 12% of reported global market demand. Saudi Arabia, the United Arab Emirates, South Africa, and other countries support connector purchases through wireless network development and equipment maintenance. High ambient temperatures, dust exposure, and demanding outdoor conditions increase the importance of reliable materials and environmental sealing. Telecom operators require durable control interfaces suitable for remote antenna installations. Selected outdoor cable assemblies specify operating temperatures reaching 70 degrees Celsius, although suitability depends on the individual product. Buyers evaluate environmental performance, cable-jacket durability, and connector protection before installation. Regional distributors support replacement requirements and equipment availability. Network modernization creates opportunities for manufacturers offering dependable components and appropriate technical assistance.
Rest of the World
Rest of the World represents an indicative 8% residual share within the five-region market allocation, including Latin America and additional territories. Brazil, Mexico, Argentina, and neighboring markets support demand through established wireless networks and infrastructure modernization. Procurement activity depends on operator investment, equipment replacement, and regional distributor coverage. Standardized connector designs help simplify maintenance across installations using compatible antenna-control equipment. Commercial AISG control cables are available in lengths ranging from approximately 0.5 meters to several tens of meters, depending on supplier specifications. This flexibility supports different tower layouts and equipment arrangements. Regional customers prioritize suitable product availability, consistent quality, and straightforward installation. Manufacturers working with local distributors can improve access to specialized connectors and complete cable assemblies.
List of Top Aisg Connector Market Companies
- Amphenol
- Rosenberger
- CommScope
- DDK
- L-com
- Shireen
- Lumberg
- Gemintek
- SYSKIM
- Recodeal
- Superlink
- XAHohor
- SomeFly Technologies
- Zeeteq
Top 2 Companies with Highest Market Share
- SYSKIM: SYSKIM holds an estimated 18% share in the referenced AISG connector competitive assessment. The company participates in the specialist telecommunications interconnection market through products intended for antenna control and related network equipment.
- Amphenol: Amphenol accounts for an estimated 15% share in the referenced competitive assessment. The company offers AISG-compatible circular connectors and RET cable assemblies for wireless infrastructure. Its product portfolio includes established C091 connector technology and multiple cable configurations.
Investment Analysis and Opportunities
Investment opportunities in the Aisg Connector Market are closely associated with wireless infrastructure maintenance, standardized connector manufacturing, and complete cable assembly production. Plug AISG Connector products account for approximately 55% of reported market demand, indicating the importance of reliable removable interconnections. Manufacturers can invest in precision machining, contact plating, automated assembly, and environmental testing to improve product consistency. Telecommunications operators increasingly require suitable replacement products for existing antenna systems, creating opportunities for manufacturers with established technical specifications. Regional distribution partnerships can improve equipment availability and reduce procurement delays. Suppliers offering dependable product documentation and long-term component support may strengthen relationships with telecommunications equipment manufacturers and installation contractors.
Asia-Pacific offers additional investment potential through its manufacturing infrastructure and substantial telecommunications equipment demand. The region represents approximately 40% of reported global connector unit consumption, supporting opportunities for specialized production and international distribution. Manufacturers can develop complete control cable assemblies, customized lengths, and compatible connector arrangements to address varied site requirements. Investment in molded strain relief, reliable sealing, and automated electrical inspection can strengthen product quality. Operators increasingly evaluate long-term maintenance requirements alongside initial procurement costs. Suppliers developing flexible manufacturing capabilities and dependable replacement inventories can improve competitiveness across geographically dispersed wireless infrastructure markets.
New Product Development
New Product Development focuses on improved environmental protection, electrical reliability, and mechanical durability. AISG-compatible connector products commonly use 8-pin circular interfaces, with manufacturers refining contact construction, housing materials, and locking mechanisms. Commercial designs increasingly emphasize IP67 protection when properly mated, corrosion-resistant components, and durable cable transitions. Product engineering aims to reduce installation errors and support consistent electrical connections in exposed telecommunications environments. Manufacturers also develop compatible preassembled control cables to simplify field maintenance. Accurate pin arrangements, dependable shielding, and suitable operating-temperature specifications remain essential design considerations.
Product innovation also addresses the needs of increasingly compact antenna installations and maintenance operations. A typical control cable assembly incorporates 2 mating connector ends, requiring consistent mechanical and electrical compatibility. Manufacturers offer different cable lengths, molded connector configurations, and jacket materials to accommodate equipment layouts. Improved strain relief can reduce mechanical stress at cable transitions, while standardized markings assist installation technicians. Testing and documentation remain important because connector performance depends on correct mating and installation. Newer product designs emphasize practical reliability rather than unnecessary complexity, reflecting the established technical requirements of AISG-controlled infrastructure.
Five Recent Developments
- September 2026 – CommScope: CommScope introduced the FOSC 550 fiber-optic splice closure to support access, metro, core, and wireless backhaul networks. The product demonstrated the potential to reduce installation time by up to 50%, improving deployment efficiency and supporting expanding telecommunications infrastructure.
- October 2026 – Rosenberger: Rosenberger inaugurated a new smart factory in Changzhou, China, on October 29, 2026, strengthening its manufacturing and research capabilities for advanced connectivity solutions. The expansion supports the growing demand for reliable telecommunications components, with the three leading AISG connector manufacturers collectively accounting for approximately 30% of the global market.
- September 2026 – Suzhou Recodeal: Suzhou Recodeal Interconnect System initiated an expansion project at its Taizhou manufacturing base on September 3, 2026. The project targets an annual production capacity of 6.7 million smart energy connection systems. The development aligns with the control cable segment, which represents approximately 50% of AISG connector market applications, highlighting the importance of standardized connectivity solutions.
- September 2026 – Dongguan RitianLink: Dongguan RitianLink Technology expanded its AISG M16-to-DB15 RET control cable assembly offerings for remote electrical tilt systems and remote radio units. The development supports standardized antenna-control connectivity, while the RET application segment is projected to account for approximately 30% of the AISG connector market in 2026.
- May 2026 – Amphenol: Amphenol continued to strengthen its AISG RET cable assembly portfolio with standardized 8-pin interfaces, IP68 protection, and resistance to harsh outdoor conditions. Its assemblies provide up to 720 hours of salt-spray resistance and 30 dB electromagnetic compatibility performance. The plug AISG connector category accounts for approximately 55% of the global market, reinforcing demand for dependable connector and cable assembly solutions.
Future Outlook
The Aisg Connector Market is expected to maintain gradual development through 2035 as telecommunications operators continue modernizing antenna infrastructure and replacing aging control components. Plug AISG Connector products are positioned to remain the leading product category, supported by approximately 55% of reported market demand. Remote electrical tilt applications will continue requiring dependable control interfaces, while replacement cable assemblies provide recurring purchasing opportunities. Manufacturers are expected to emphasize environmental durability, consistent electrical performance, and compatibility with established network equipment. Demand will remain influenced by wireless infrastructure investment, maintenance schedules, and the operational lifespan of existing antenna installations.
Future product development will increasingly emphasize standardized interfaces, efficient manufacturing, and dependable outdoor performance. AISG-compatible systems will continue using established 8-pin connection arrangements where specified by antenna equipment manufacturers. Suppliers are expected to improve contact reliability, cable durability, and installation convenience while maintaining compatibility with existing infrastructure. Asia-Pacific manufacturing capabilities and established international distribution networks will influence competitive positioning. Manufacturers offering reliable quality assurance, flexible assembly options, and accessible technical support can strengthen their presence as telecommunications operators maintain and modernize geographically distributed antenna systems.
Aisg Connector Market Report Coverage
| REPORT COVERAGE | DETAILS | |
|---|---|---|
|
Market Size Value In |
USD 1042.63 Million in 2026 |
|
|
Market Size Value By |
USD 1232.04 Million by 2035 |
|
|
Growth Rate |
CAGR of 1.87% from 2026-2035 |
|
|
Forecast Period |
2026 - 2035 |
|
|
Base Year |
2025 |
|
|
Historical Data Available |
Yes |
|
|
Regional Scope |
Global |
|
|
Segments Covered |
By Type :
By Application :
|
|
|
To Understand the Detailed Market Report Scope & Segmentation
Download FREE Sample
|
||
Frequently Asked Questions
The global Aisg Connector Market is expected to reach USD 1232.04 Million by 2035.
The Aisg Connector Market is expected to exhibit a CAGR of 1.87% by 2035.
Amphenol, Rosenberger, CommScope, DDK, L-com, Shireen, Lumberg, Gemintek, SYSKIM, Recodeal, Superlink, XAHohor, SomeFly Technologies, Zeeteq
In 2026, the Aisg Connector Market value will reach at USD 1042.63 Million.

Related Reports

Our Clients






























.svg)
